Spare Room, Real Numbers: What a Lodger Actually Leaves You in 2026
Rent-a-room has a way of sounding simpler than it is. You have a spare bedroom, someone needs a place to stay, and the taxman gives you a generous allowance. In practice, the gap between gross rent and what you keep is where most households get caught out. This is not an argument for or against taking in a lodger. It is a netting exercise: what does the room actually contribute once the obvious and the overlooked costs are on the page?
Start with the relief, not the rent
Under the UK rent-a-room scheme, you can receive up to £7,500 in a tax year from letting furnished accommodation in your main home and pay no tax on that income. The threshold is £7,500 per household, not per room. If you own the home jointly, the allowance can be split. The relief is optional. If your expenses are higher than the allowance, you can choose the actual-expenses route instead, but you need records and the maths has to beat the simple version. For many spare-room lets, the allowance wins on admin alone.
A practical example. Say you charge £650 a month, which is £7,800 over a full year. Under the relief, £7,500 is tax-free and £300 is taxable at your marginal rate. At basic rate that is £60 of tax, before any other income. At higher rate it is £120. If you charge £600 a month, £7,200 a year, you are under the threshold and the tax bill is nil. That does not mean the arrangement is free of tax consequences elsewhere—more on that below—but the income tax position is straightforward.
What the £7,500 actually covers
It covers furnished accommodation in your only or main home. Not a whole flat you have moved out of, not a holiday let, not a room in a property that is not your main residence. The lodger must share the home with you; if you give them exclusive possession of a self-contained flat, you are in a different legal and tax world. The relief is for living accommodation, not storage or a converted garage unless it genuinely forms part of the home.
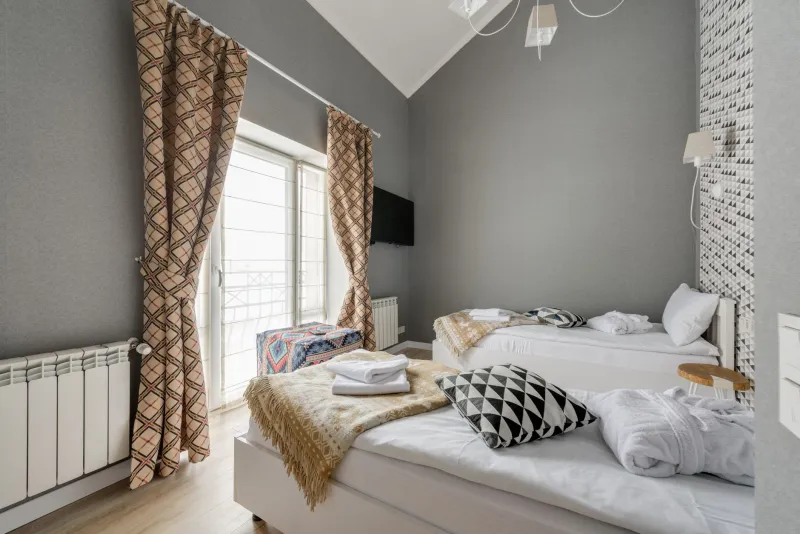
Furnished is a word people skate over. It does not require a designer bedroom, but it does mean the room is ready to live in: bed, storage, somewhere to work or sit, and shared use of kitchen and bathroom. If you are renting out an empty box and calling it furnished, the relief is not the issue—the arrangement is. Keep a simple inventory and photos. It helps with insurance claims and it makes the wear-and-tear conversation less abstract.
Bills are a negotiation, not a guess
The rent figure is only half the story. A lodger adds to gas, electricity, water, broadband and the general friction of a shared kitchen. You can include bills in the rent or charge a separate contribution, but decide before they move in. A common approach is a single all-inclusive rent, reviewed annually, with a clear note on what happens if energy prices move sharply. The alternative is a lower rent plus a fair share of bills, which is more transparent but more admin.
For a netting exercise, assume the room does not run itself. Even a low-use lodger adds something to standing costs. If you are on a water meter, a second long shower is not free. If you work from home, broadband contention is real. Build a monthly figure into your maths—even a rough £40 to £80—so the rent does not flatter the result.
Insurance, mortgage and the fine print
Tell your home insurer before someone moves in. Standard home insurance is not built for paying lodgers, and some policies ask for a higher premium or exclude theft by a lodger. The same goes for landlords if you rent your home: subletting or taking in a lodger may breach your tenancy. If you have a mortgage, check the lender's terms. Many residential mortgages allow a lodger, but consent requirements vary, and an undeclared lodger can become a problem at remortgage time.
If you are leasehold, read the lease. Some leases restrict occupation or require notice. If you are a social tenant, check the tenancy agreement before advertising. These are not hypotheticals; they are the reasons lodger arrangements unwind after a month.
Benefits, council tax and the reporting habit
Means-tested benefits are where the spare-room maths gets serious. Rent-a-room income can affect Universal Credit, council tax reduction and other support, and the rules are not identical across every benefit. Report the change. Do not assume the £7,500 tax relief means the income is invisible to the benefits system. It is not.
Council tax also deserves a check. A lodger is an adult in the home, so the single-person discount may no longer apply. That can be a 25% hit on the council tax bill. In some households the rent more than covers it; in others it quietly eats a chunk of the gain. Add it to the netting sheet before you set the rent.
A simple netting exercise
Take gross annual rent, subtract the tax you will actually pay under the route you choose, then subtract the extra bills, the insurance uplift, the council tax change and a wear-and-tear allowance. Wear and tear is not a tax deduction under the relief route, but it is a real cost. A lodger will scuff walls, fill the washing machine and shorten the life of a mattress. A 10% set-aside is a blunt but useful starting point.
Example: £7,800 rent, £60 tax at basic rate under the relief, £720 extra bills, £120 insurance uplift, £390 lost single-person discount, £780 wear and tear. Net: £5,730. Still worthwhile for many households, but not the £7,800 headline. If the room would otherwise sit empty, that is a fair return. If you are giving up a home office or a family room, the trade-off is less obvious.
The admin checklist
Write a simple lodger agreement covering rent, bills, notice period and house rules. Keep a rent record and a copy of the agreement. Register for Self Assessment if your gross rent is over the threshold or if you choose the actual-expenses route. Tell your insurer, lender, leaseholder or landlord as applicable. Report changes to benefits and council tax. Photograph the room and inventory before move-in.
None of this is designed to put you off. A lodger can turn a spare room into genuine household income, and the rent-a-room relief is one of the more generous bits of the tax code. But the number that matters is not the rent. It is what stays in your account after the bills, the fine print and the wear and tear have had their say. Run that figure for your household before you run the advert.